3 Experts on Managing 1099 Behavioral Health Networks
How to Build, Manage, and Maintain Them
The classification, 1099, and foreign-payee rules that matter when an expert network pays consultants and fractional executives.
Six rules matter when a U.S. expert network or fractional executive platform pays consultants as independent contractors: contractor status under IRS rules, 1099-NEC reporting, payments to experts who work through a company, the filing deadline, backup withholding, and withholding when an expert is a foreign individual with nonresident status for U.S. tax purposes. The IRS reporting threshold for a 1099-NEC is $2,000 on payments an expert network or fractional placement firm makes in 2026 (IRS, Am I required to file a Form 1099 or other information return?). Rules are as of October 2026.
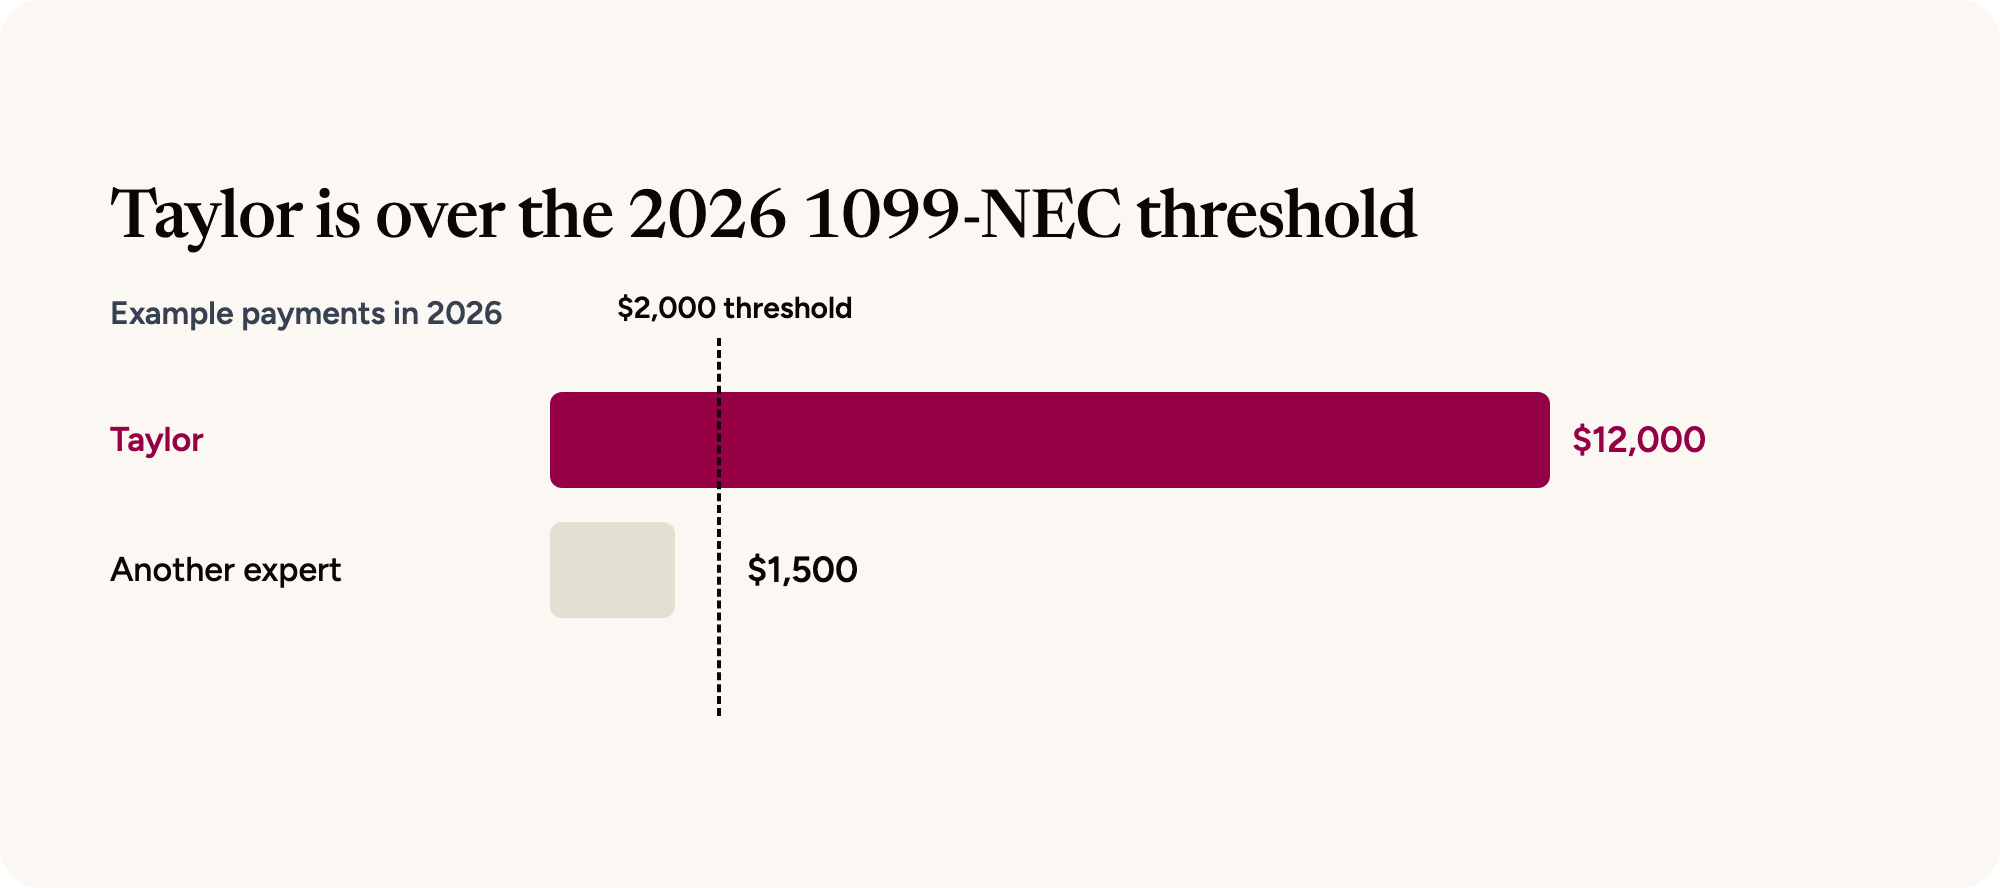
Most examples below use Taylor, a fractional CFO who advises companies through your network and is paid $12,000 in 2026.
For a fractional CFO like Taylor or a consultant taking advisory calls, the IRS looks at three groups of facts: behavioral, financial, and type of relationship. Behavioral facts ask whether the company directs the worker's tasks and methods. For example, the company might set the agenda for an advisory call. Financial facts look at whether the payer controls the business side of the job: the expert's pay arrangement, expense reimbursement, and the tools and supplies. Type of relationship is the third group: written contracts, employee-type benefits, whether the relationship will continue, and whether the work is a key aspect of the business. Each fact is weighed alongside the others, and the IRS says to look at the whole arrangement, including how far the company can direct and control the worker (IRS, Independent contractor (self-employed) or employee?).
Taylor's $12,000 in 2026 fractional CFO fees is well past the $2,000 line for fees paid to someone who is not your employee. A $600 cutoff applied to payments made before 2026. An expert paid $1,500 for a few consultations in 2026 is under the line, though if backup withholding (explained below) took federal income tax out of that pay, the IRS says to file a 1099-NEC at any amount (IRS, Am I required to file a Form 1099 or other information return?).
Wingspan's tax compliance platform page lists creation, reconciliation, filing, and delivery as the automated steps for 1099-NEC, 1099-MISC, and 1099-K forms, and says TINs are verified automatically, with mismatches flagged before a contractor gets paid.
BetterUp, a coaching network with roughly 4,000 coaches across 70+ countries, had its 2025 1099-NEC forms auto-generated for eligible US contractors, verified against the IRS in real time, and filed electronically. Mento, a coaching company with over 100 coaches on its contractor roster, reports 80+ hours saved monthly on invoice and W-9 validation.
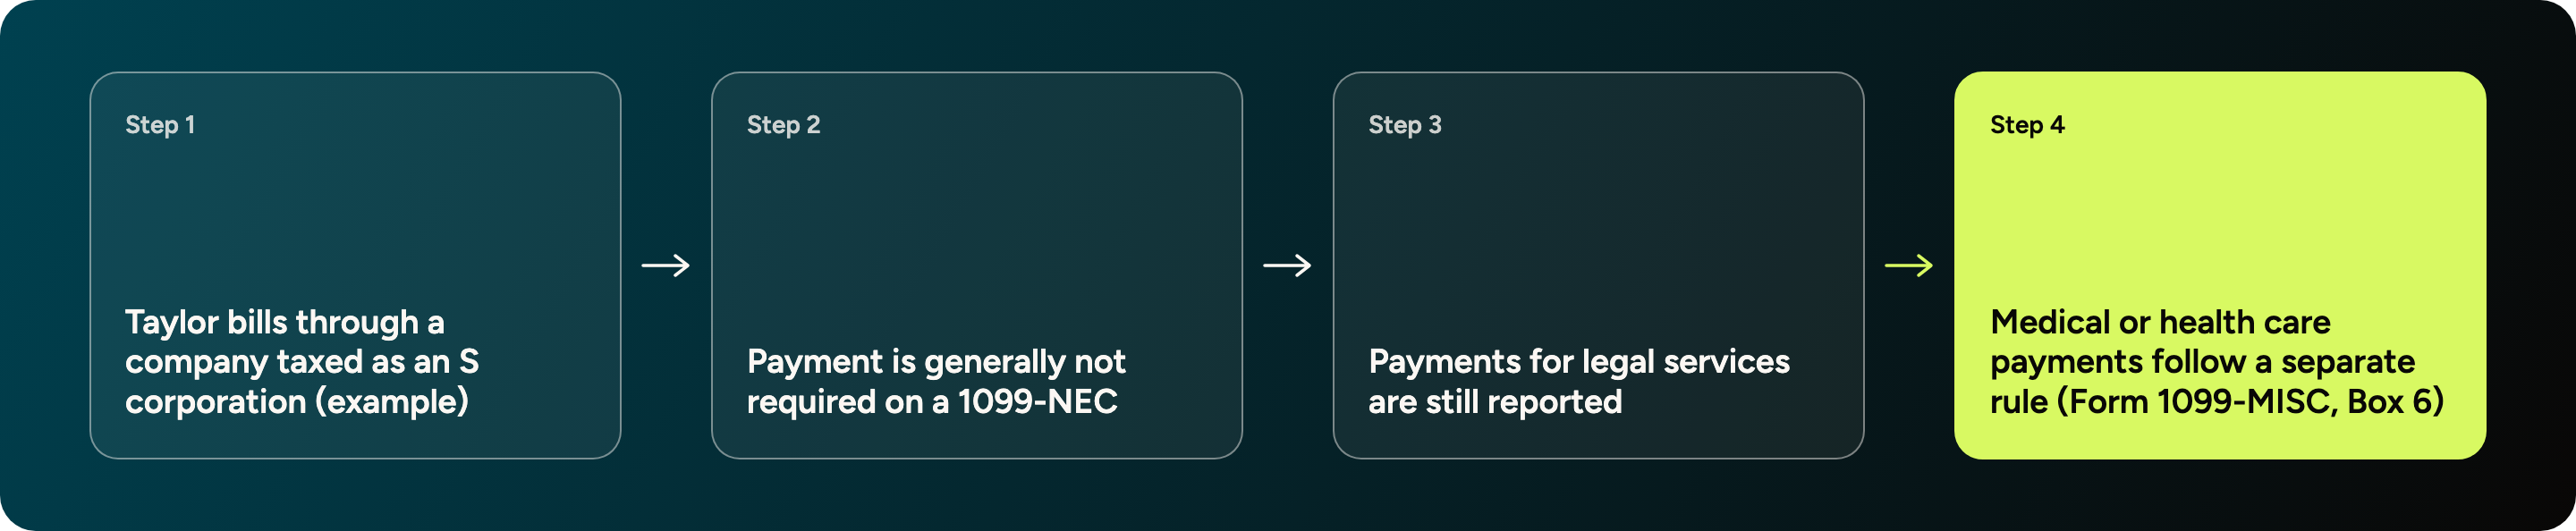
Some fractional executives bill through their own company. The IRS says you don't need an information return when the business you pay is incorporated, unless the payment is for medical or legal services (IRS, Am I required to file a Form 1099 or other information return?). The instructions for the 1099-NEC describe that exemption as covering a corporation, which includes an LLC treated as a C or S corporation (IRS, Instructions for Forms 1099-MISC and 1099-NEC). A payment to Taylor's S corporation is generally not reported on a 1099-NEC. A payment to a fractional general counsel's corporation for legal services is still reported. Under the Form 1099-MISC instructions, medical or health care services fall outside the corporation exemption and, at $2,000 or more, are reported in Box 6 of that form.
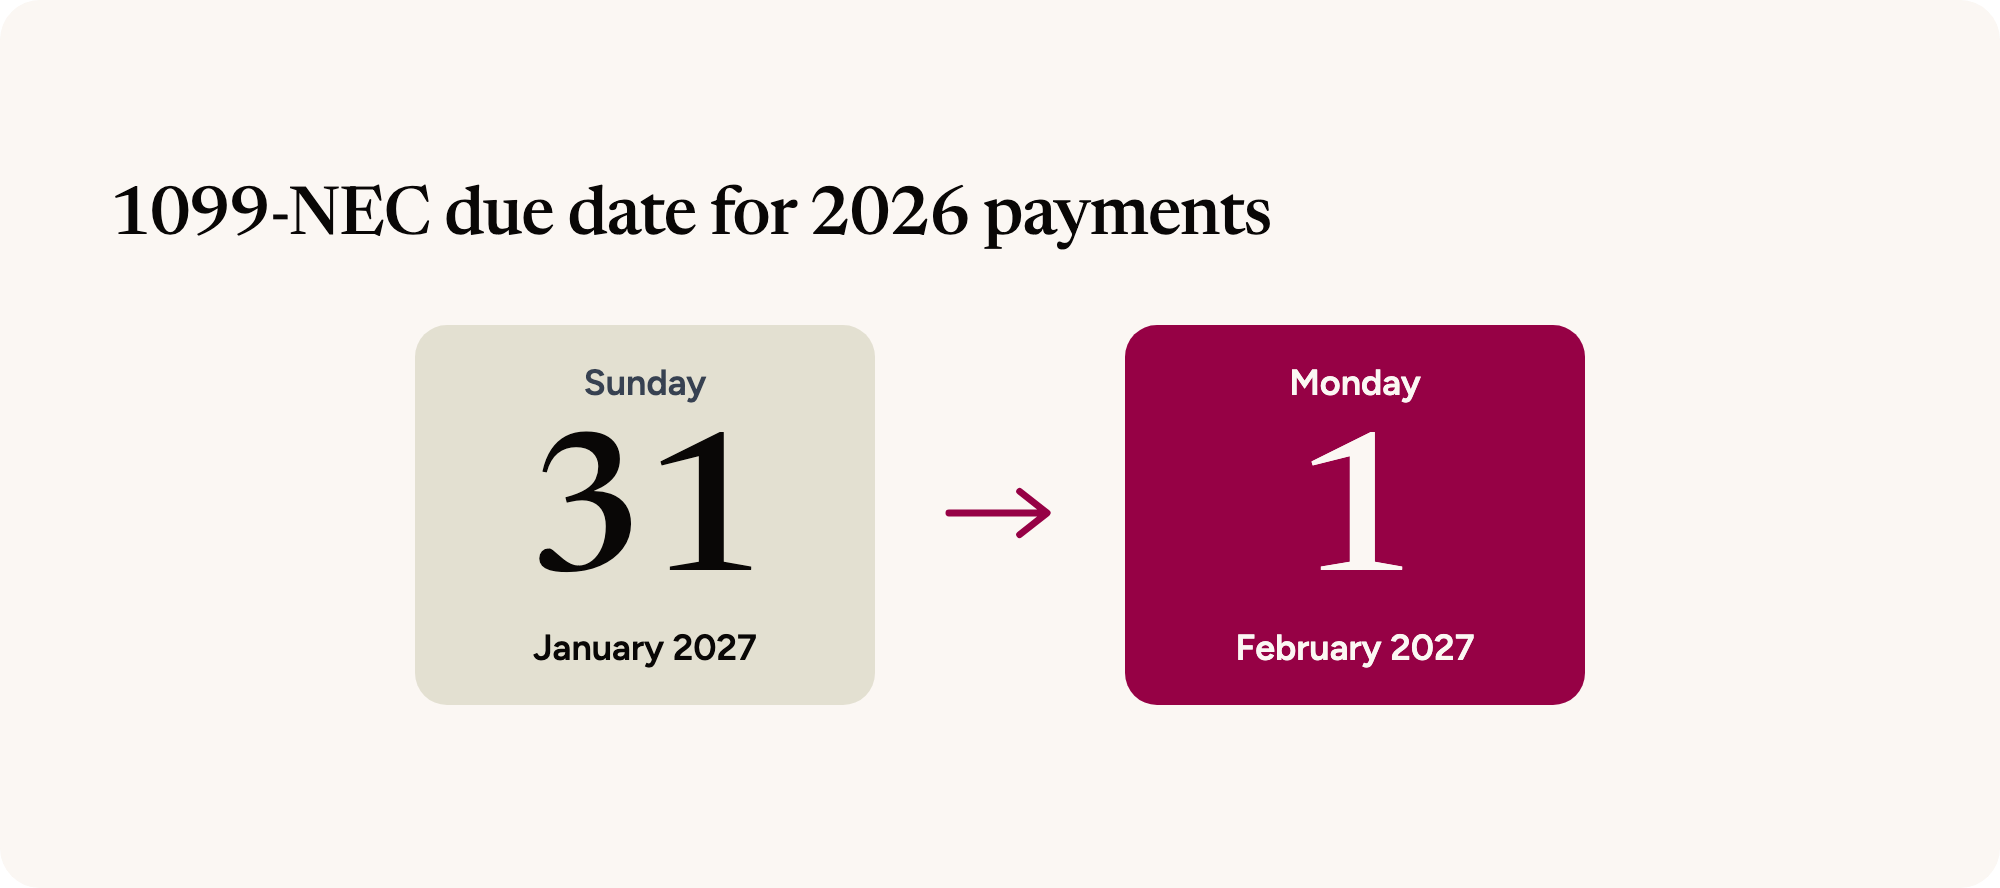
The January 31 deadline covers the 1099-NEC forms for fees a network paid its consultants in the prior year. The IRS moves the deadline to the next business day when January 31 falls on a weekend or legal holiday (IRS, Instructions for Forms 1099-MISC and 1099-NEC). In 2027 that date is a Sunday, which puts the 1099-NEC for Taylor's 2026 fees, and for any other expert whose 2026 payments are reportable, due Monday, February 1, 2027.
Once a network has 10 or more information returns to file, it must file them electronically, and the IRS page says that count includes Forms W-2 (IRS, Am I required to file a Form 1099 or other information return?).
If a consultant does not report a taxpayer identification number (TIN) as required, you are under a 24% withholding duty on reportable nonemployee compensation paid to U.S. persons. The duty also applies if an IRS notice says a TIN is incorrect and the payee does not certify it in reply (IRS, Forms and associated taxes for independent contractors). If it applied to Taylor, a $2,000 retainer payment would have $480 held back.
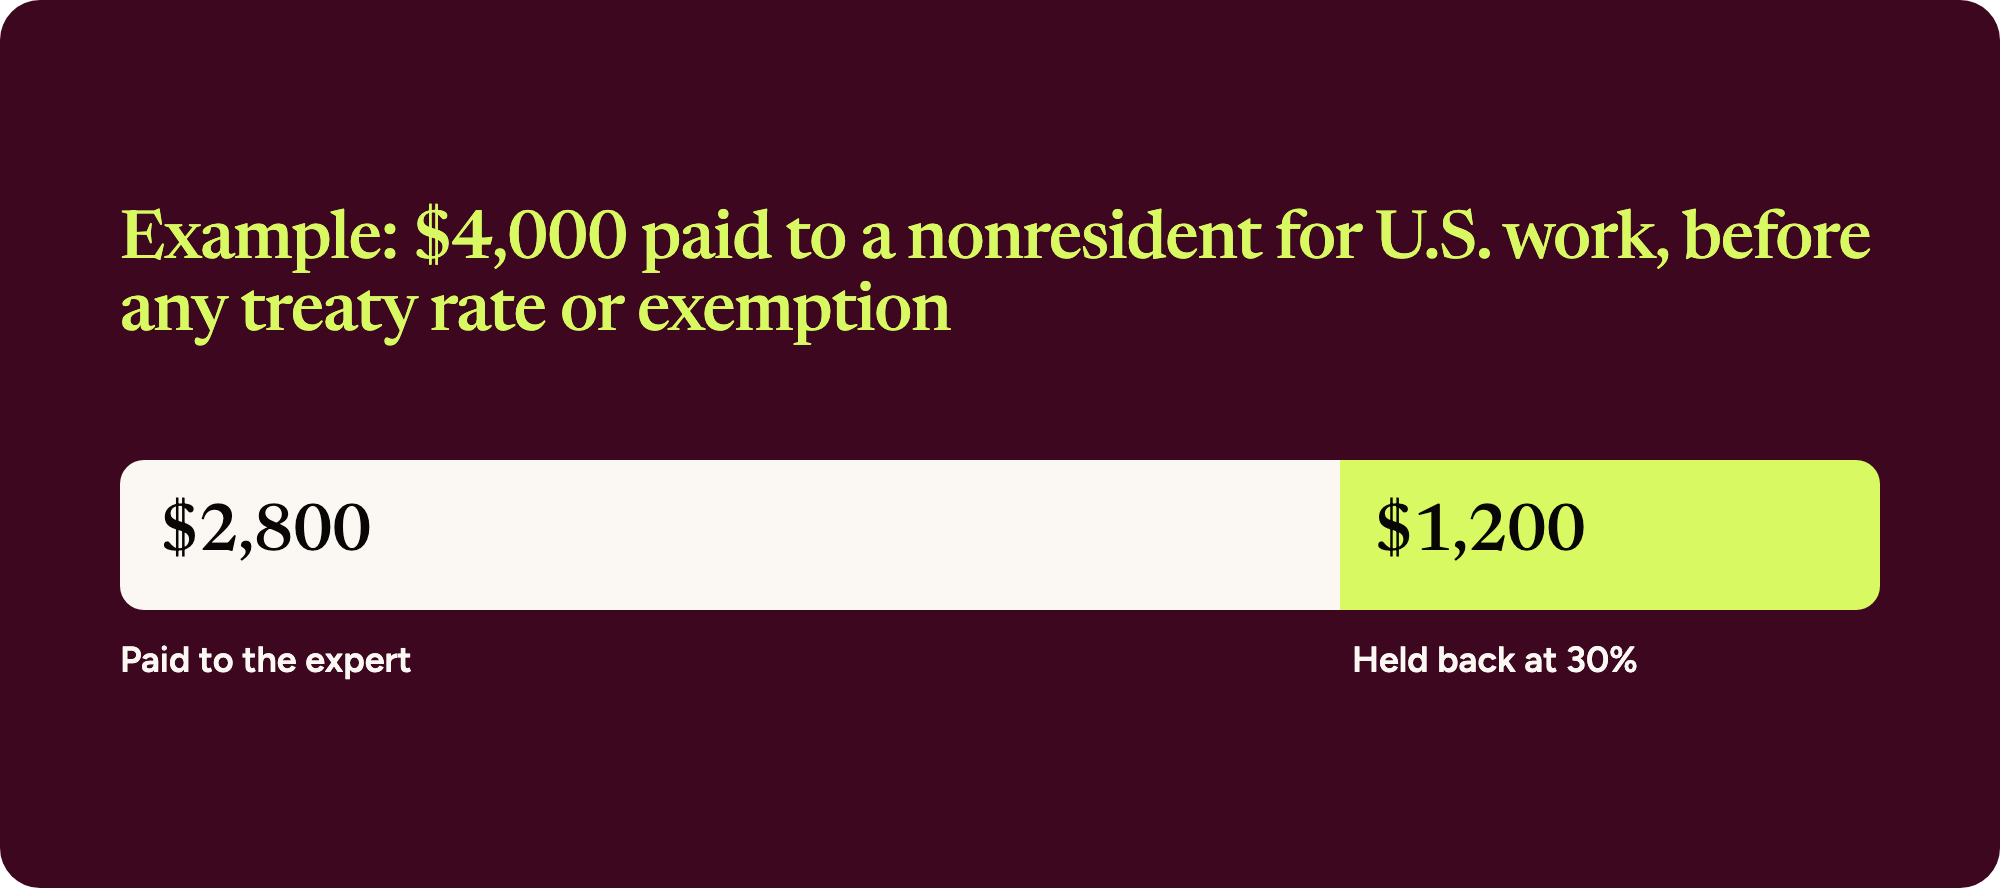
For independent personal services performed by a nonresident foreign contractor for U.S. tax purposes, the IRS says payments may be subject to 30% withholding unless a lower rate is provided by tax treaty or the law (IRS, Forms and associated taxes for independent contractors). Publication 515 says that, with exceptions, income for personal services performed in the United States is from U.S. sources, that the place where the services are performed determines the source, and that most types of U.S. source income received by a foreign person are subject to U.S. tax of 30% (IRS, Publication 515 (2026)). If a foreign expert with nonresident status for U.S. tax purposes did the work in the United States, a $4,000 payment could have $1,200 held at 30%, before any treaty rate or exemption.
Withholding can follow at either 30% or the backup rate when a requested Form W-8BEN is not provided. The instructions also say not to use that form to claim an exemption from withholding on compensation for independent or dependent personal services performed in the United States, and to provide Form 8233 or Form W-4 instead (IRS, Instructions for Form W-8BEN). Form 1042 must be filed if the payer is required to file Form 1042-S, and a Form 1042-S is required even if the tax was not actually withheld (IRS, Forms and associated taxes for independent contractors).
Wingspan collects applicable W-8 forms, tax details, bank information, and eSignatures during onboarding for international contractors. Wingspan's documentation lists W-8BEN for individuals only and does not list Form 8233. BetterUp's page says its 1099-NEC flow automatically left out coaches outside the US.
Whether a given fractional role or advisory arrangement counts as contracting turns on the relationship itself, and an expert's treaty rate turns on the treaty and the form that expert submits. This post covers federal tax rules. It doesn't cover state tax rules, securities laws that apply to expert network calls, or payroll for employees. Wingspan's filing documentation says it cannot process backup withholding or Form 1042 and treats legal services filings as outside its scope, so those steps sit outside what Wingspan files.
Expert onboarding and payments from one system
See how expert networks and fractional executive platforms onboard experts, collect W-9s and applicable W-8 forms, and file 1099s in Wingspan.
Explore Wingspan for expert networks and fractional executives →
How to Build, Manage, and Maintain Them
Build a W-9 collection and TIN matching workflow with clear owners, secure updates, mismatch resolution, and records ready for 1099 review.
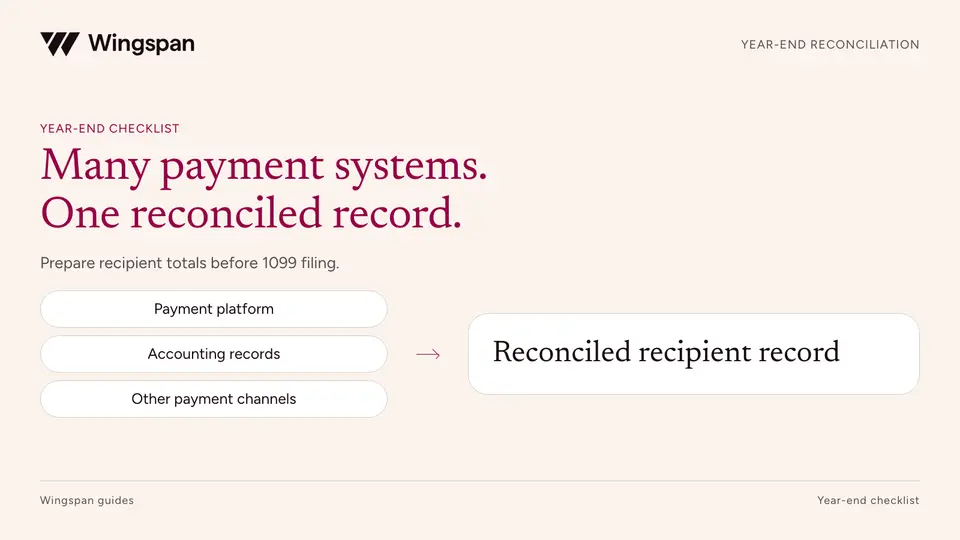
Reconcile contractor payments across platforms, AP, banks, and legacy systems with source registers, recipient mapping, and a reviewable bridge.