3 Experts on Managing 1099 Behavioral Health Networks
How to Build, Manage, and Maintain Them
The licensing, lead-safety, and tax rules to check when a field services company pays property preservation workers.
Six rules to check when a mortgage field services company pays property preservation workers as independent contractors: state contractor licensing, EPA lead-safe certification, IRS worker classification, the 1099-NEC, electronic filing, and backup withholding. A field services company generally reports a worker's 2026 payments on a 1099-NEC once they reach $2,000 (IRS, Am I required to file a Form 1099?). Rules are as of October 2026.
Most examples below use Casey, who owns a trash-out and winterization business set up as an LLC, takes work orders from your company in California, and is paid $4,200 in 2026.
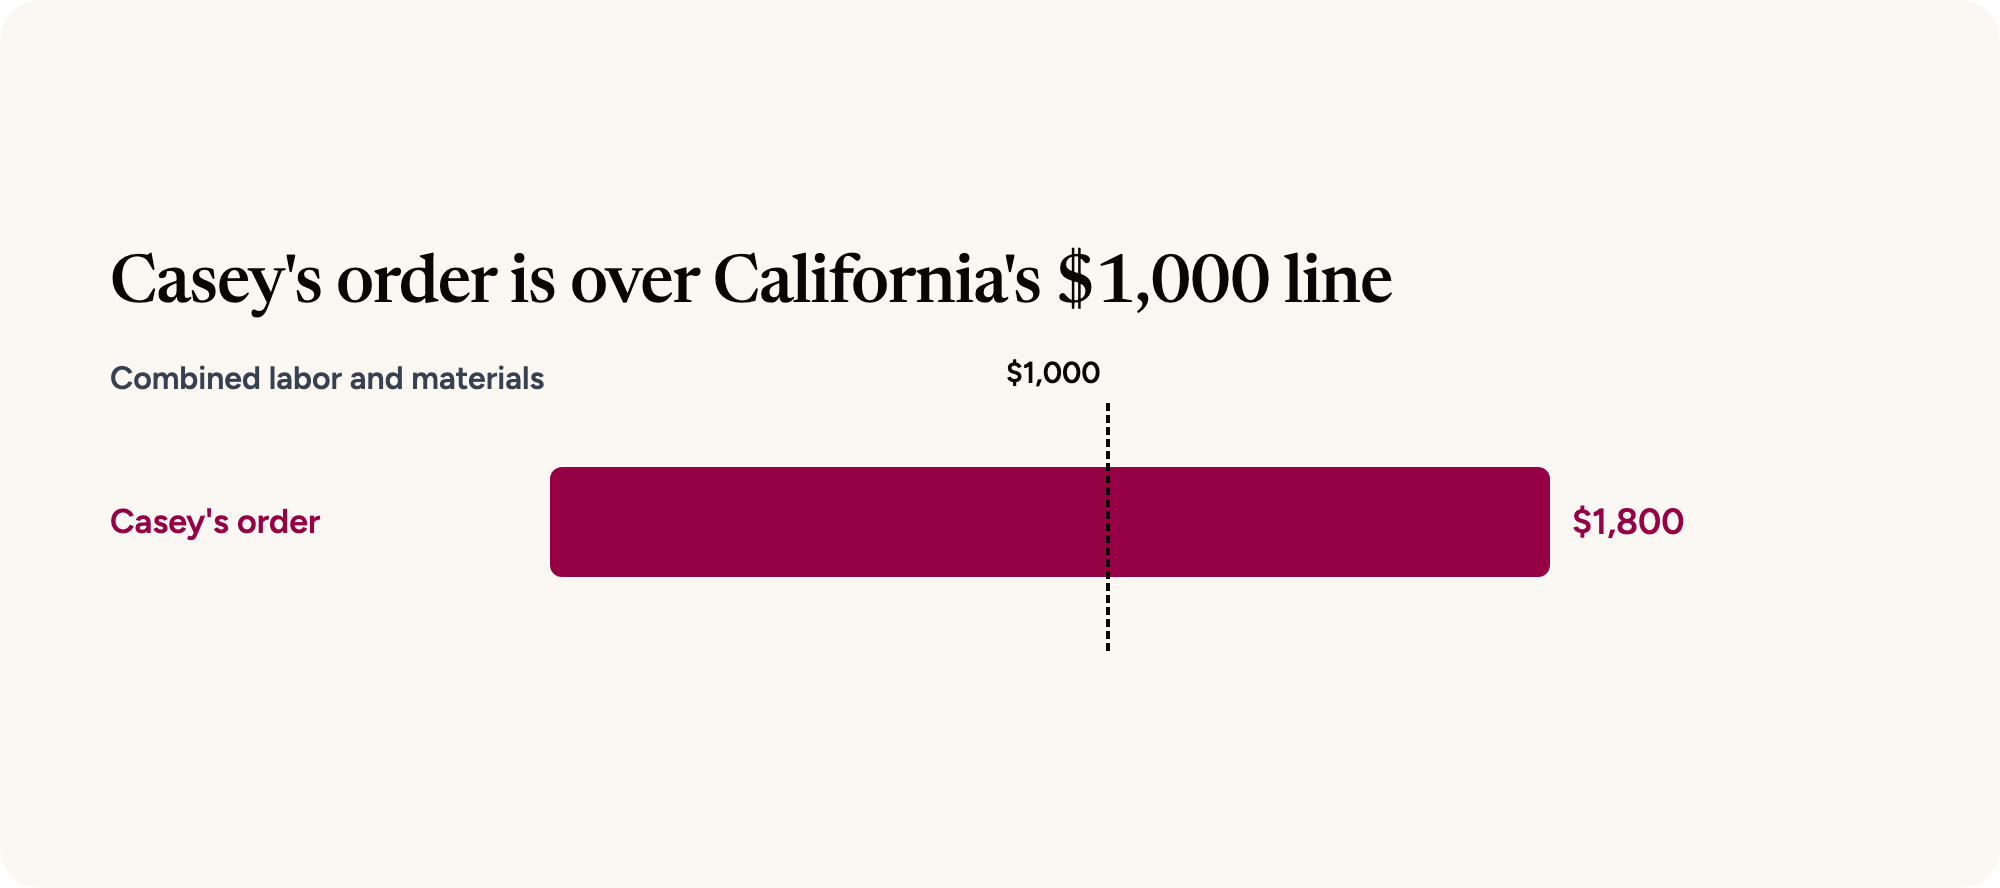
California requires a license from its Contractors State License Board for anyone who contracts to perform work on a project that requires a building permit, uses employee labor or workers, or is valued at $1,000 or more in combined labor and materials costs (CSLB, What Kind of Contractor Do You Need?). If Casey's contract for a board-up and repair job is valued at $1,800 in combined labor and materials, it is above that $1,000 threshold.
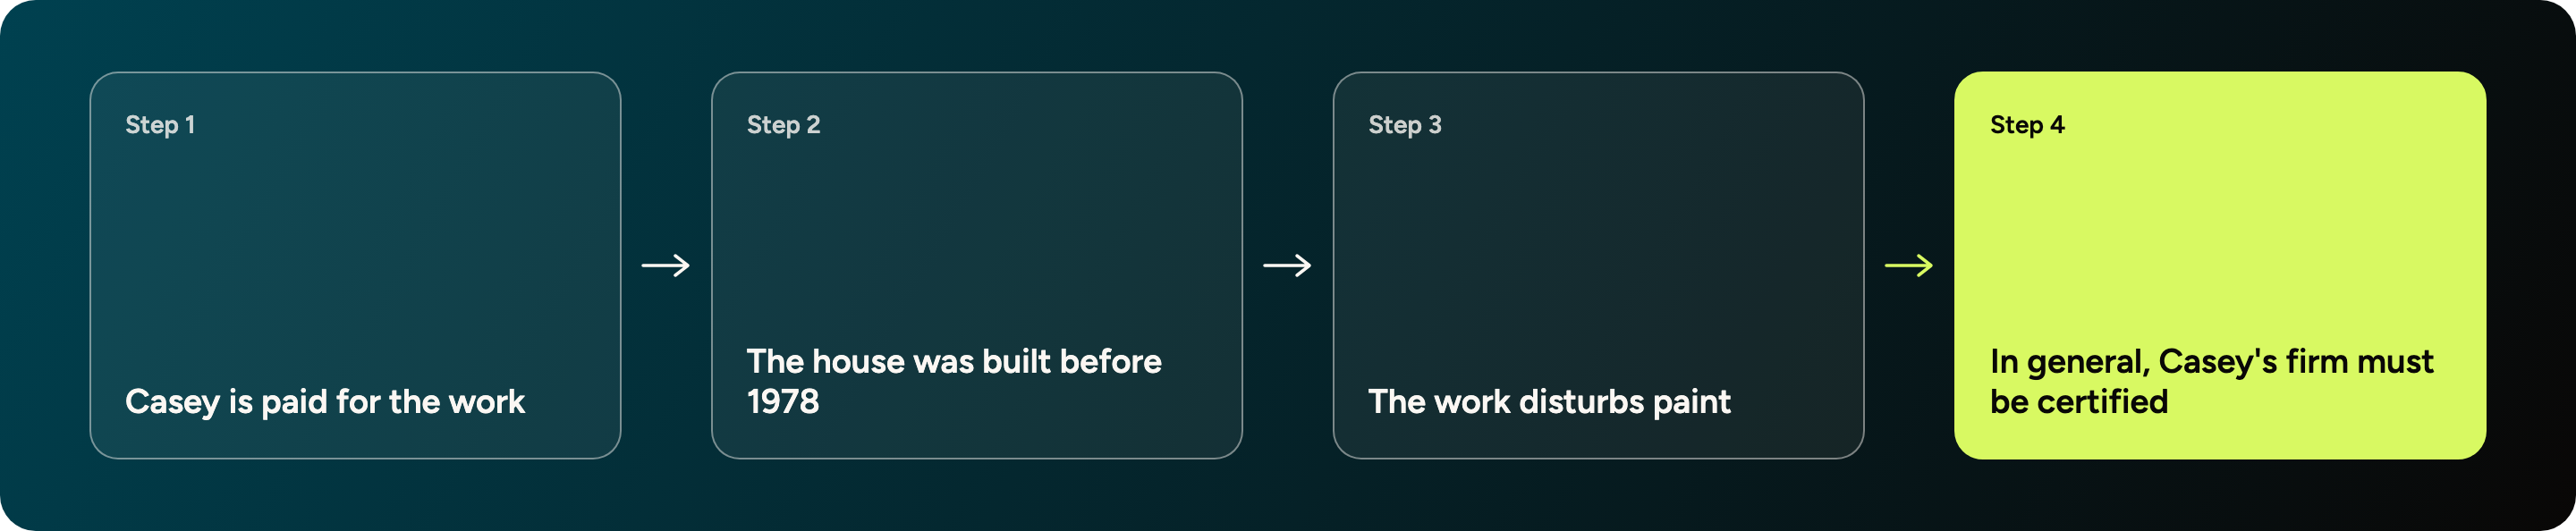
In general, anyone paid to perform work that disturbs paint in housing and child-occupied facilities built before 1978 must be certified, and that includes all firms, even sole proprietorships (EPA, Lead Renovation, Repair and Painting Program). EPA also says property management companies that perform, offer, or claim to perform that work must become lead-safe certified firms. For a property management company, whether it counts depends on what it performs, offers, or claims to perform. The rules page says firms performing renovation, repair, and painting projects that disturb lead-based paint in homes built before 1978 must be EPA- or state-certified (EPA, Lead Renovation, Repair and Painting Program Rules). If Casey's firm is paid to scrape and repaint exterior trim on a house built in 1965, the work disturbs paint, so in general the firm needs certification, as a sole proprietorship too.
For a worker like Casey, the IRS looks at three kinds of facts about control and independence: behavioral, financial, and type of relationship. Behavioral facts ask whether the company can direct the way Casey does the job. For Casey, that could mean how a trash-out is sequenced or how a winterization is carried out. Financial facts ask who controls the money side of Casey's job, including who provides tools and supplies and how Casey is paid and reimbursed. Whether Casey has a written contract, and whether any employee-type benefits apply, falls in the last group, type of relationship. Across all three groups, the IRS points to the full relationship, and to how far the company may direct and control Casey, as the keys (IRS, Independent contractor (self-employed) or employee?).
Payments Casey receives in 2026 are measured against $2,000. The threshold for payments made earlier than 2026 was $600 (IRS, Am I required to file a Form 1099?). The same page lists an exception for payments made to another business that is incorporated, when the payment is not for medical or legal services. In the instructions, that means payments to a corporation, and an LLC taxed as a C or S corporation counts as one (IRS, Instructions for Forms 1099-MISC and 1099-NEC). Whether Casey's LLC falls under that wording depends on how it is treated for tax purposes. If it does, the exception generally covers Casey's $4,200. If it doesn't, $4,200 is over the 2026 threshold, and a worker paid $1,500 would be under it.
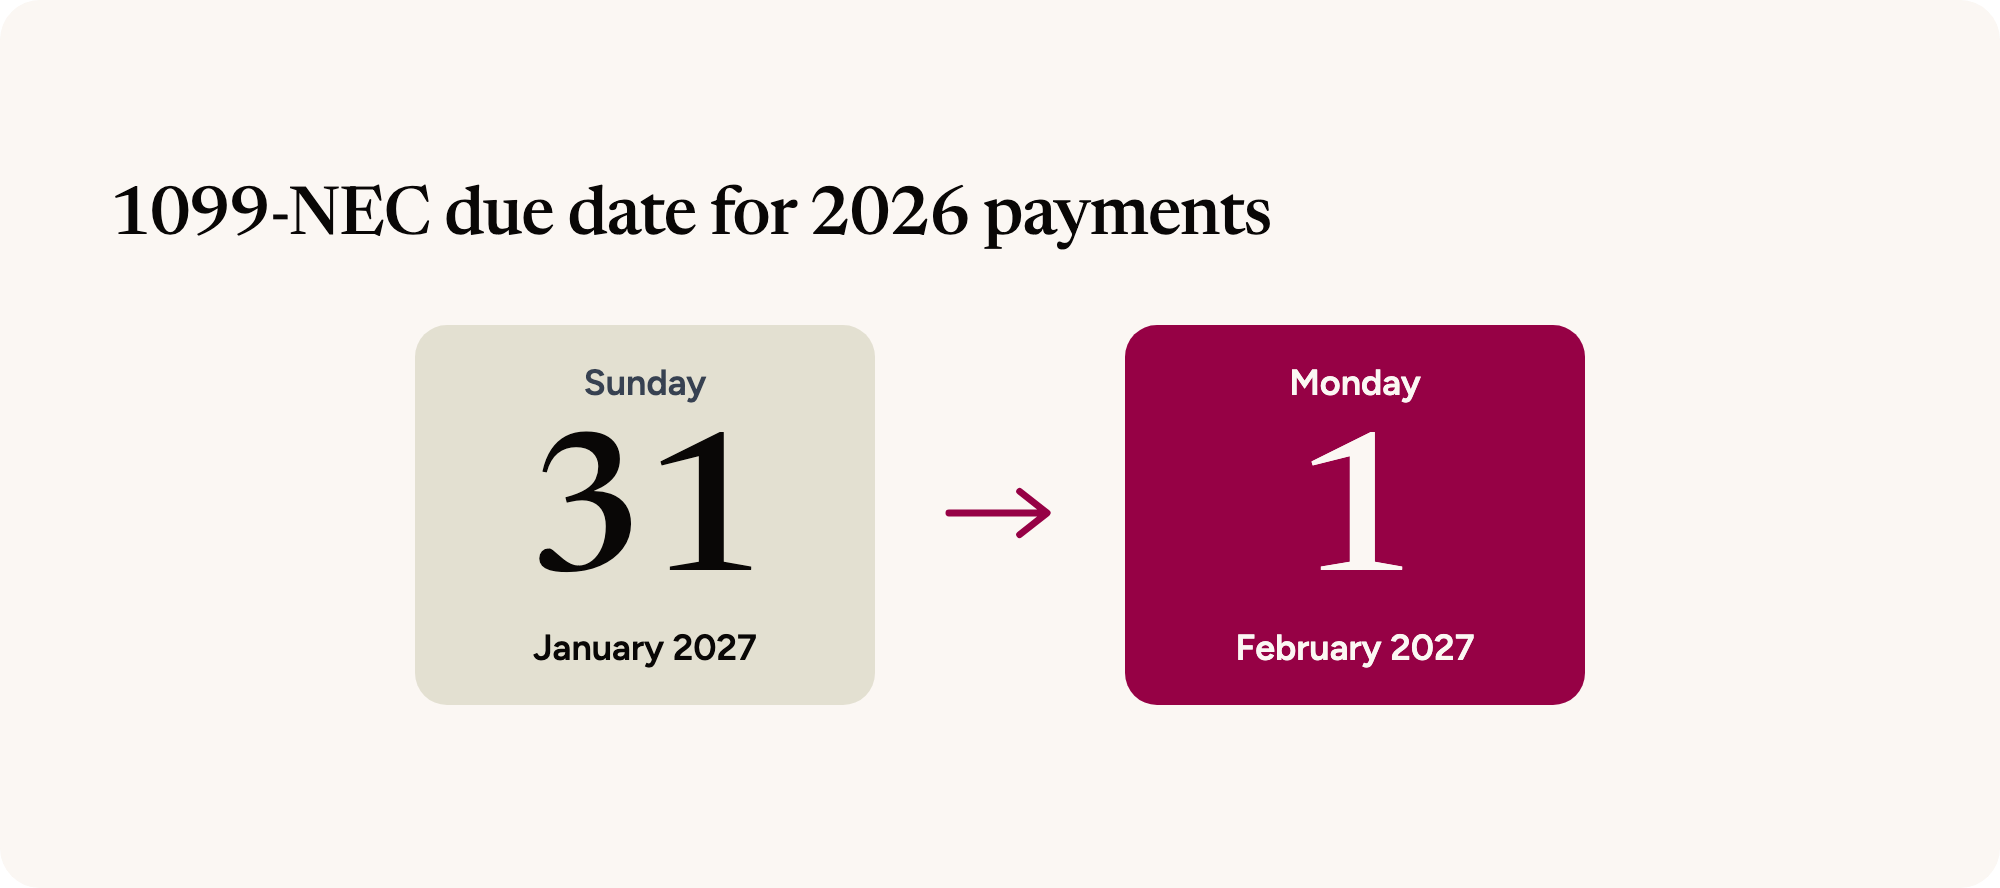
January 31 is the 1099-NEC due date. In 2027 it lands on a Sunday, and a due date that falls on a Saturday, Sunday, or legal holiday moves to the next business day (IRS, Instructions for Forms 1099-MISC and 1099-NEC). A form covering Casey's 2026 work orders, if one is required, would therefore be due Monday, February 1, 2027.
Once your company has 10 or more information returns, electronic filing is required (IRS, Am I required to file a Form 1099?). The instructions say the IRS lowered that threshold to 10 and calculates it by aggregating all information returns, so 1099-NECs for your trash-out and winterization crews are counted together with every other information return you file (IRS, Instructions for Forms 1099-MISC and 1099-NEC).
For a company that files many 1099s, Wingspan automates the creation of 1099 forms and also automates reconciliation, filing, and delivery, covering 1099-NEC, 1099-MISC, and 1099-K. Safeguard Properties reports 60+ hours saved during tax season by automating 1099 processing and IRS validation, and describes its process before Wingspan as manual 1099 processing across encrypted, siloed systems.
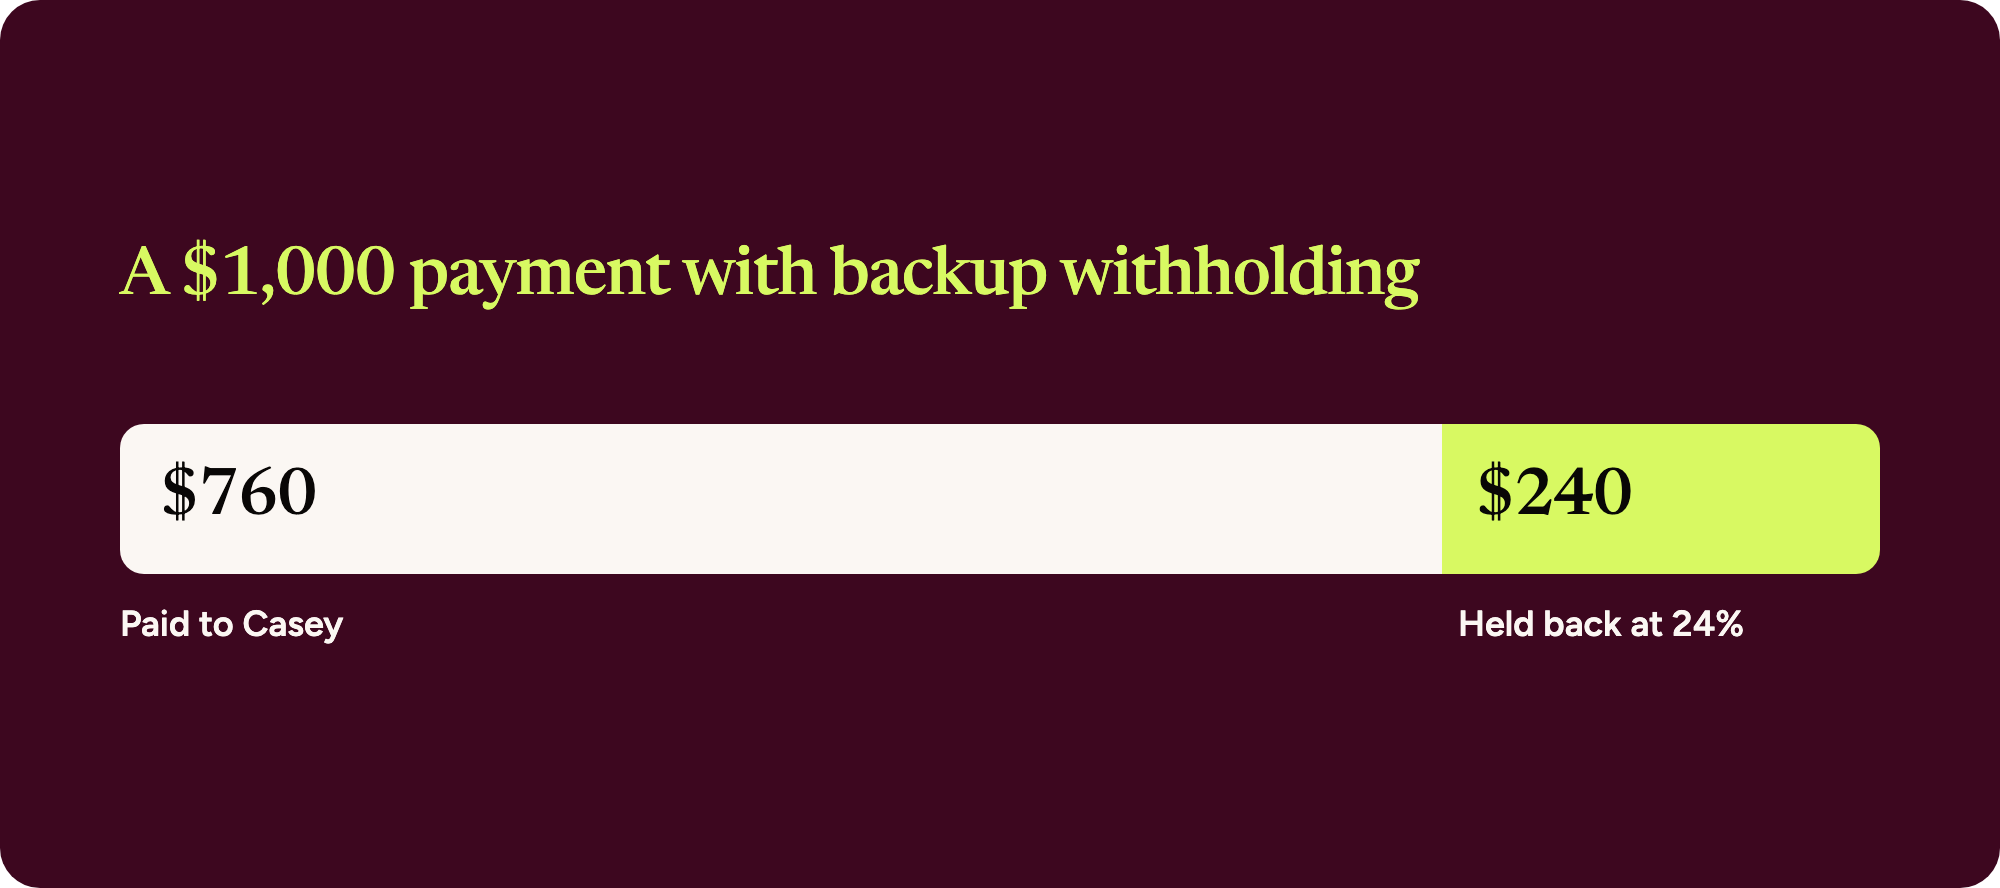
Backup withholding applies to a U.S. contractor who has not supplied a taxpayer identification number (TIN) in proper form, or whose TIN the IRS flags as incorrect when the contractor then fails to certify it: 24% comes out of reportable payments of nonemployee compensation (IRS, Forms and associated taxes for independent contractors). The instructions add that a 1099-NEC is required for each person from whom you withheld federal income tax, regardless of the amount of the payment (IRS, Instructions for Forms 1099-MISC and 1099-NEC). If Casey's LLC is not taxed as a corporation and backup withholding applied to a $1,000 winterization payment, $240 would be held back (24% of $1,000).
Wingspan's tax compliance page describes W-9 collection during onboarding, automatic TIN verification, and mismatch flags raised before a contractor is paid.
State law governs licensing, so a vacant-property job outside California needs its own check; this post cites California's rule only. How a worker is classified turns on the relationship with the company, and the post also leaves out OSHA, insurance requirements, and payroll for employees.
Property preservation worker onboarding and pay in one place
See how field services companies onboard workers, verify TINs, and file 1099s in Wingspan.
How to Build, Manage, and Maintain Them
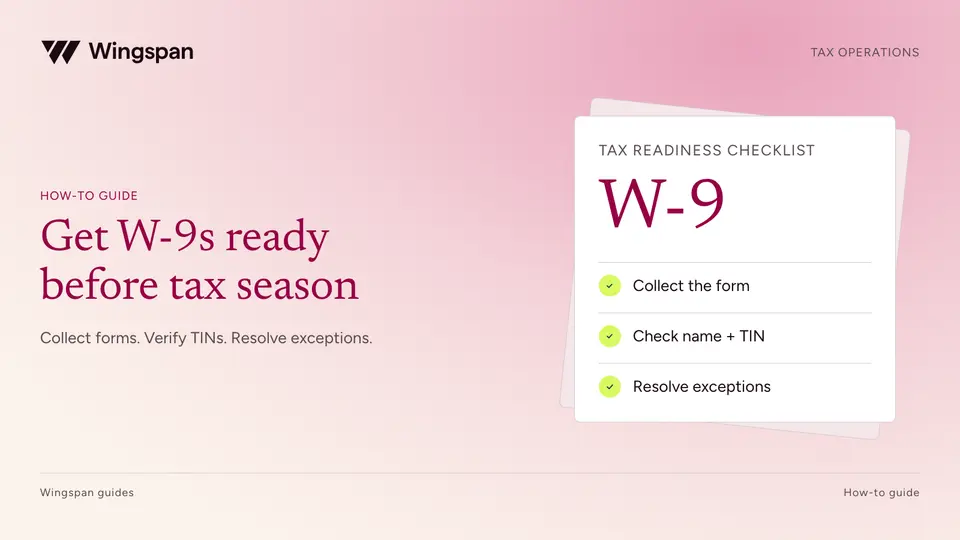
Build a W-9 collection and TIN matching workflow with clear owners, secure updates, mismatch resolution, and records ready for 1099 review.
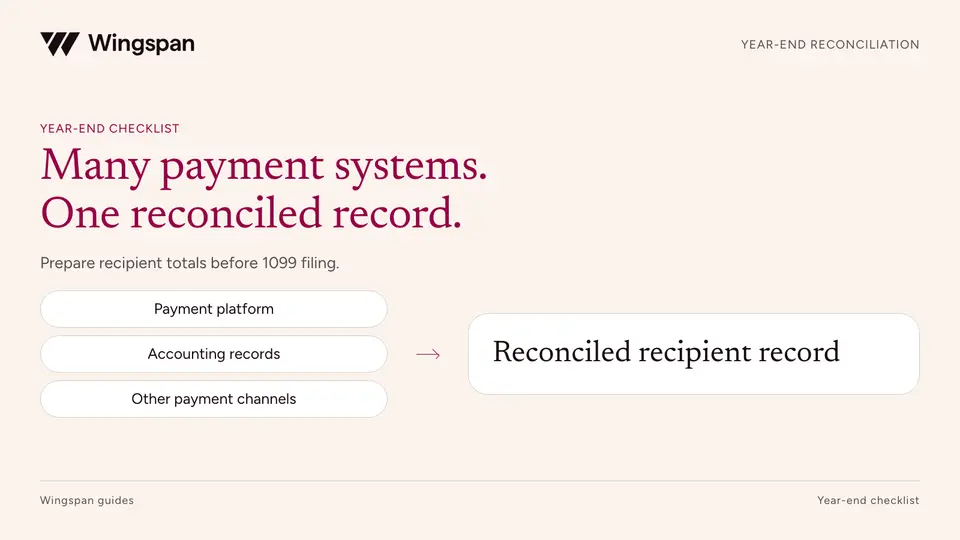
Reconcile contractor payments across platforms, AP, banks, and legacy systems with source registers, recipient mapping, and a reviewable bridge.