3 Experts on Managing 1099 Behavioral Health Networks
How to Build, Manage, and Maintain Them
The tax-form, sanctions, and copyright rules that matter when a localization company pays translators and linguists.
Six rules matter when a U.S. localization company pays translators and linguists as independent contractors: the IRS factors that classify a worker, 1099-NEC reporting, Form W-8BEN for workers abroad, Form 1042-S for U.S.-source pay to foreign workers, OFAC sanctions, and copyright ownership of translations. The 1099-NEC filing threshold for translator payments made in 2026 is $2,000 (IRS, Am I required to file a Form 1099 or other information return?). Rules are as of October 2026.
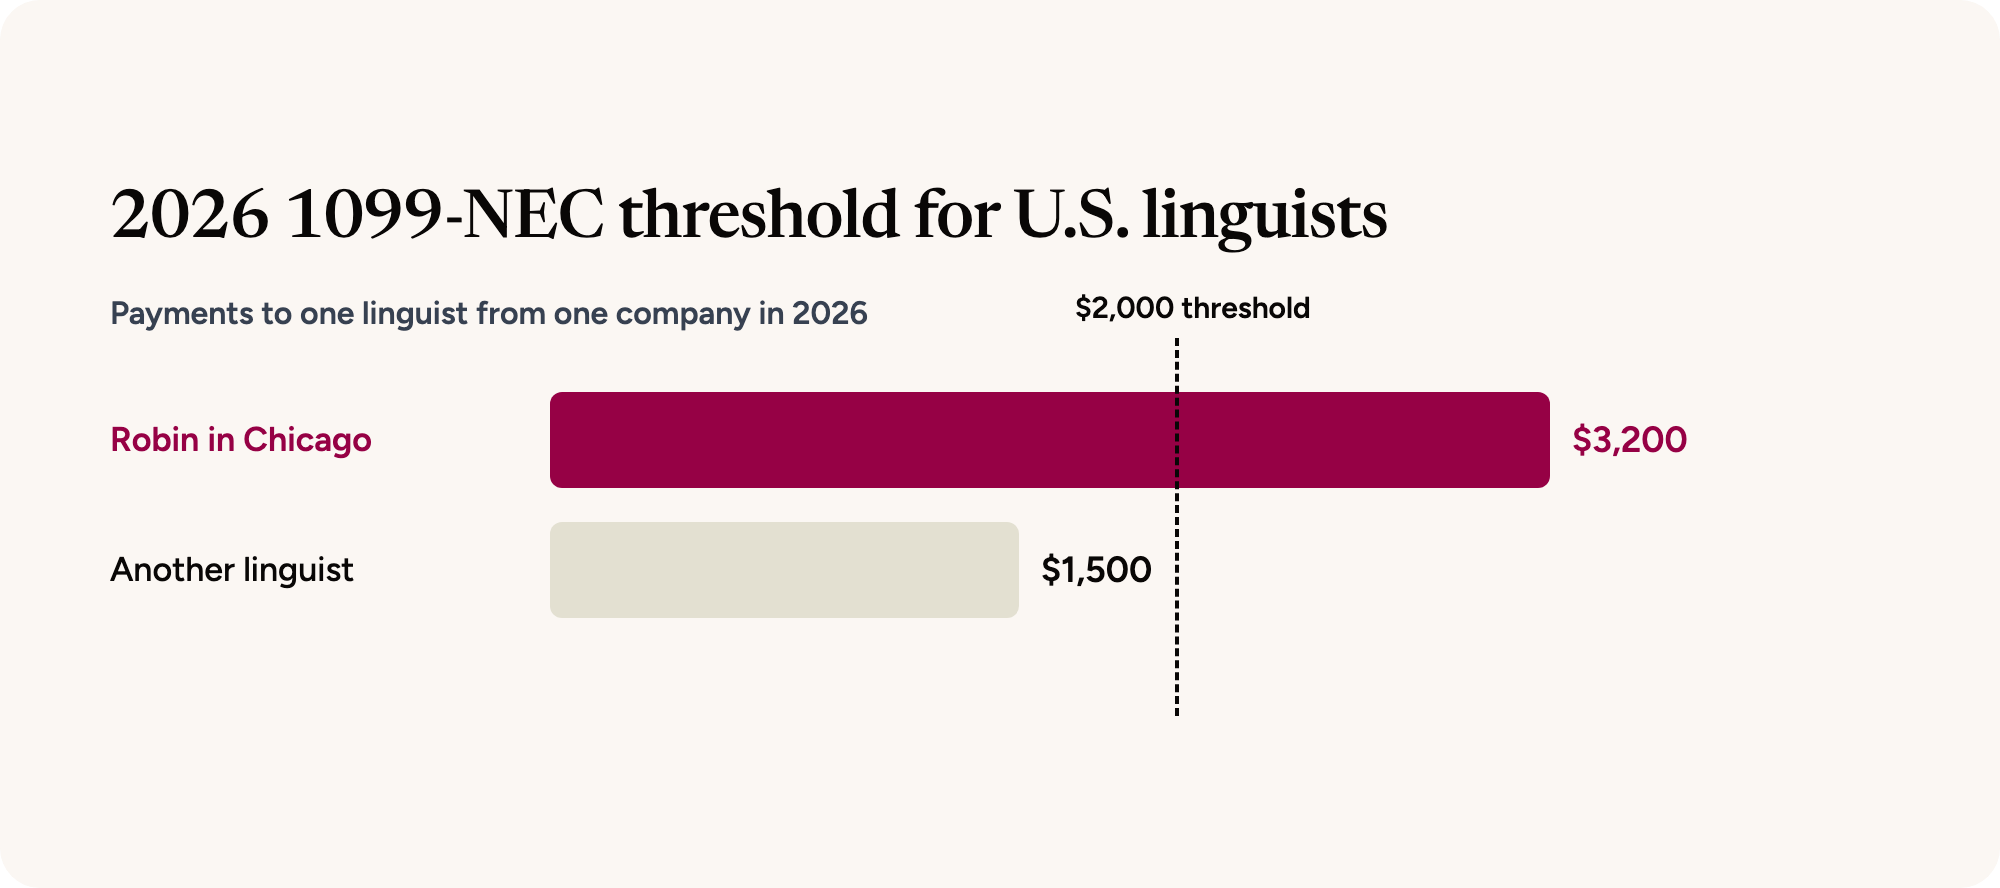
Most examples below use Robin, a Portuguese-English translator in Lisbon who is paid $3,200 in 2026.
A translation engagement can leave evidence in each of the three groups the IRS uses to judge a working relationship: behavioral, financial, and type of relationship. Behavioral facts turn on whether the localization company has the right to direct and control how the translator does the work. Whether a project manager's instructions or a style guide's rules amount to control is a question this group asks. On the financial side, the business aspects of the engagement matter: which party provides the translation software, whether the rate is per word or per hour, and whether expenses are reimbursed. Written contracts and employee-type benefits belong to the third group, type of relationship. The IRS says no single fact settles the question, and that the keys are the entire relationship between the parties and how far the company has the right to direct and control the worker (IRS, Independent contractor (self-employed) or employee?).
Had Robin been a Chicago translator paid $3,200 for 2026 projects, that total would clear the $2,000 mark the IRS sets for payments made in 2026. Before 2026 the mark was $600 (IRS, Am I required to file a Form 1099 or other information return?). A linguist paid $1,500 over the year falls under that mark, though a 1099-NEC is still required at any amount if federal income tax was withheld under the backup withholding rules (same page). Backup withholding takes 24% of certain reportable payments to a U.S. person, for example a payee who hasn't given the payer a taxpayer identification number (TIN) the way the IRS requires, usually on Form W-9, or whose TIN the IRS says is incorrect (IRS, Publication 515).
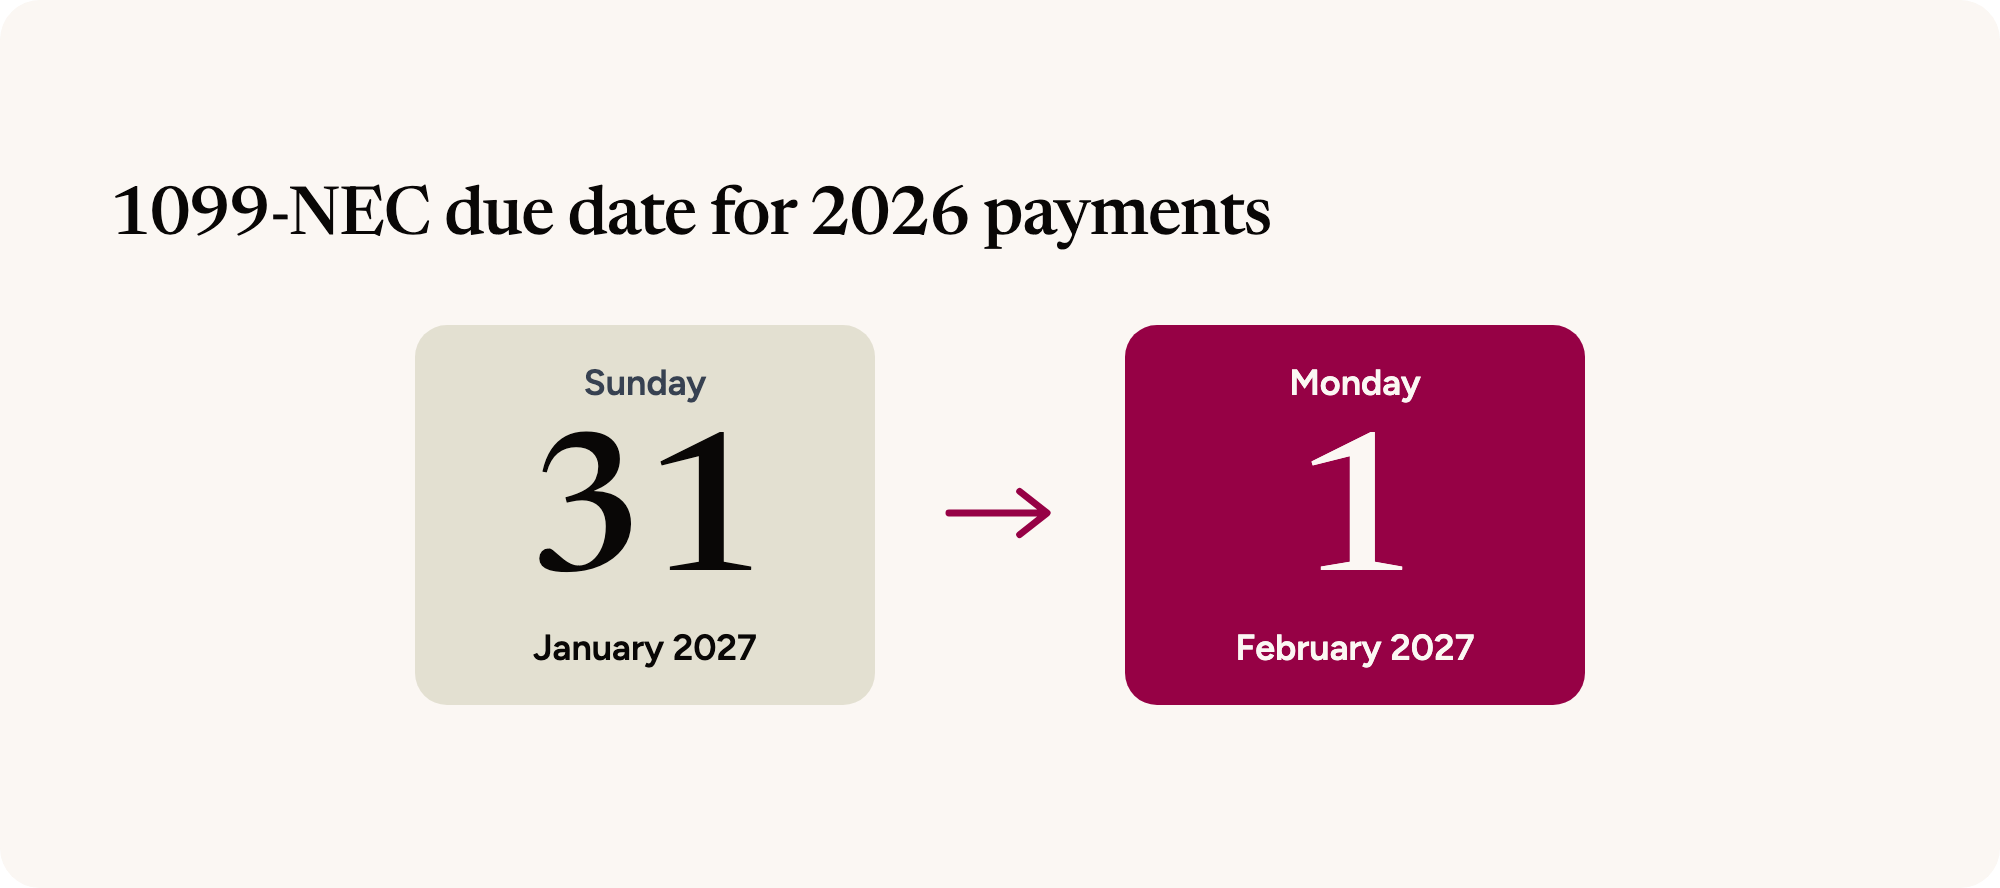
A 1099-NEC for a translator's 2026 work is due January 31, 2027, though a weekend or legal holiday shifts a due date to the next business day (IRS, Instructions for Forms 1099-MISC and 1099-NEC). That January 31 is a Sunday, so a localization vendor's forms for its U.S. translators are due Monday, February 1, 2027.
For a localization vendor with translators on many projects, Wingspan handles 1099 creation, then reconciles, files, and delivers 1099-NEC, 1099-MISC, and 1099-K forms, and it verifies TINs automatically, flagging mismatches before a worker is paid.
A foreign individual who is the beneficial owner of an amount subject to withholding gives Form W-8BEN to the withholding agent or payer when asked, whether or not the person claims a reduced rate or an exemption (IRS, About Form W-8 BEN). A valid Form W-8 from a foreign person means no backup withholding and no Form 1099 reporting (IRS, Publication 515). Robin in Lisbon, if not a U.S. person, could give a W-8BEN instead of a Form W-9, which is how a U.S. person provides a TIN.
In onboarding, Wingspan gathers the W-8 forms that apply, along with tax details, bank information, and eSignatures, and pays workers in 180+ countries and territories.
BetterUp pays about 4,000 coaches spread over 70+ countries. Dedicated webinars walked U.S.-based coaches through W-9 collection and IRS verification, and global coaches through the W-8 flow and their local-currency payout options. In the 2025 1099-NEC filing Wingspan handled for BetterUp, coaches outside the US were automatically excluded from the 1099-NEC flow.
Form 1042-S, Foreign Person's U.S. Source Income Subject to Withholding, is due March 15 of the following year (IRS, Instructions for Form 1042-S (2026)). The place where the services are performed generally determines the source of personal service income (IRS, Source of income, Personal service income), and foreign source income is generally not required to be reported on Form 1042-S (IRS, Instructions for Form 1042-S). Robin's $3,200 for work done in Portugal is foreign source.
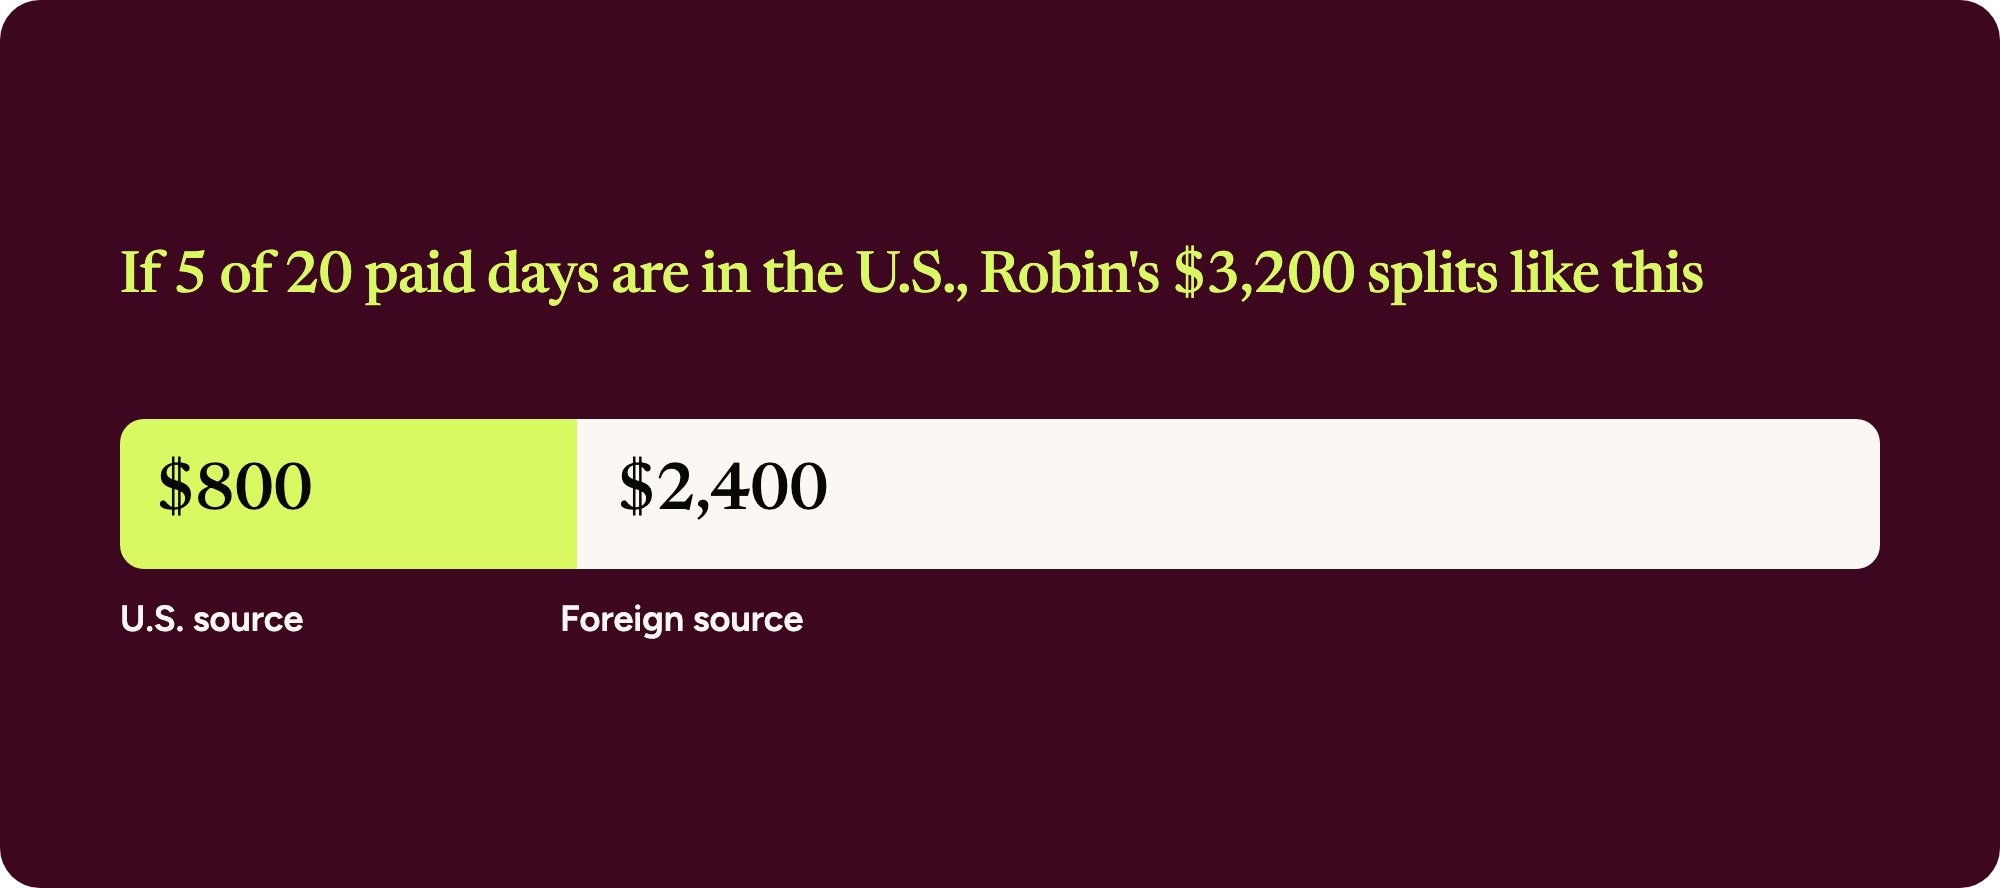
If Robin spent 5 of 20 paid days in the United States, the IRS says to allocate on a time basis in most cases, so $800 of the $3,200 is U.S. source. For independent personal services, Publication 515 says to withhold 30% of the payment unless a withholding agreement, final payment exemption, or treaty applies (IRS, Publication 515). That would be $240 on the $800.
OFAC sanctions bind every U.S. person, and FAQ 11 says that group includes U.S. citizens and permanent residents wherever they are located, entities and individuals inside the United States, and U.S. incorporated entities with their foreign branches (OFAC, FAQ 11). Property of a blocked person, including anyone on OFAC's SDN List, that is in the possession or control of a U.S. person must be blocked (frozen) and may not be transferred, and a report must reach OFAC within 10 business days after the property becomes blocked (OFAC, FAQ 9). If Robin were a blocked person, the $3,200 would have to be blocked rather than paid, unless OFAC authorizes it.
Ordinarily the author is the person who created the work, and a work made for hire is an exception. A commissioned work is made for hire only if it falls in one of nine categories, translation among them, and the parties expressly agree in a written instrument signed by all of them that it is. If any requirement is missing, it is not (U.S. Copyright Office, Circular 30, Works Made for Hire, revised 08/2024).
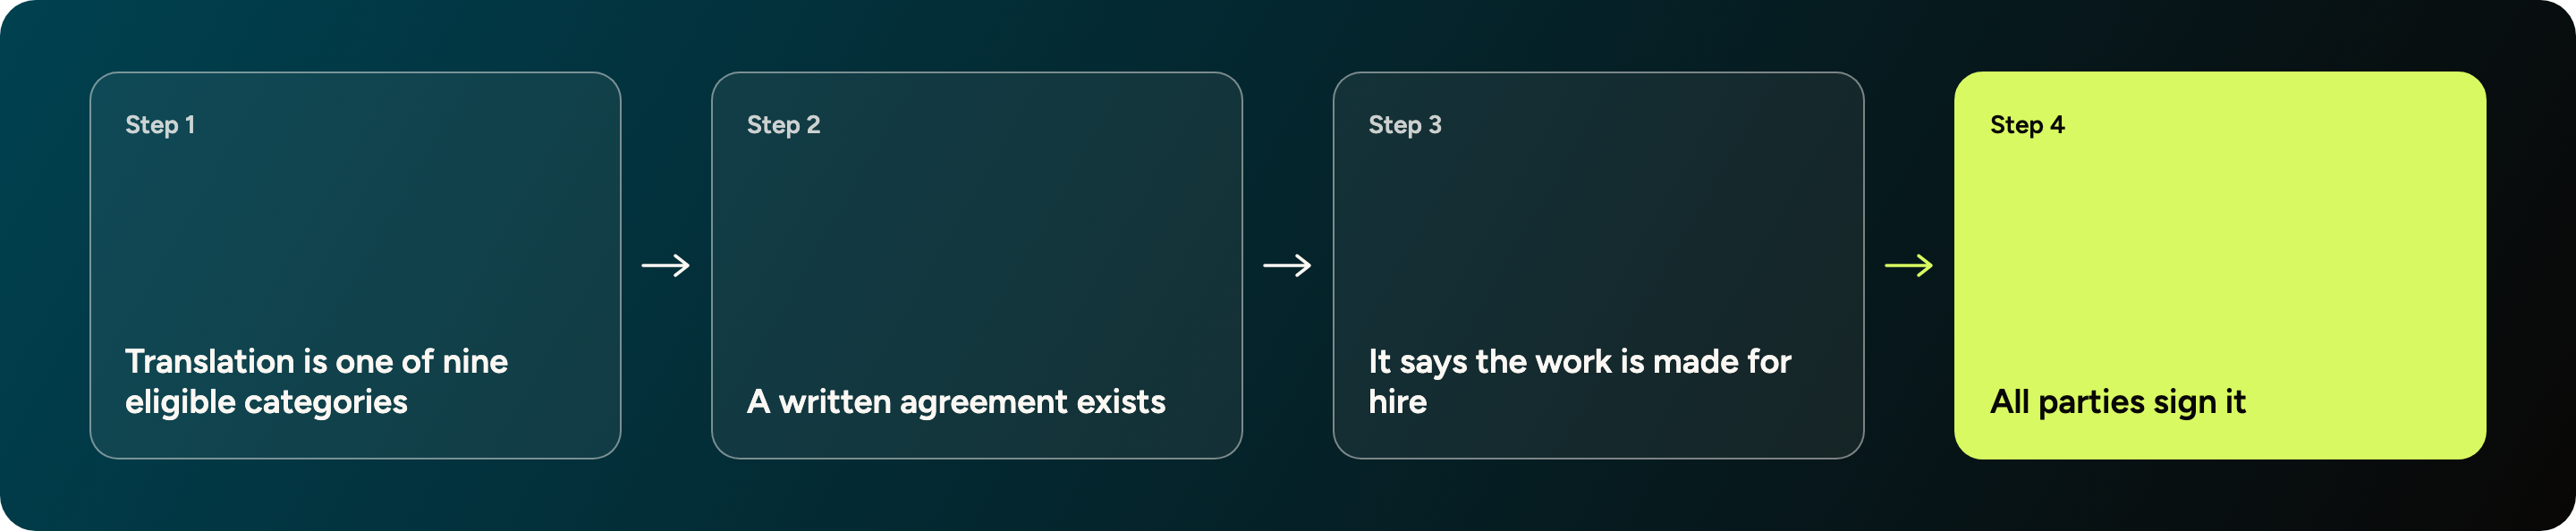
A transfer of copyright ownership, other than by operation of law, is not valid unless it is in writing and signed by the owner of the rights conveyed or the owner's duly authorized agent (U.S. Copyright Office, 17 U.S.C. 204(a)). For an independent contractor, a translation is a work made for hire only under a signed written agreement that says so. Otherwise the translator is the author, and a transfer needs a signed writing.
Whether a given translator counts as a contractor turns on the working relationship. State taxes, the law where a translator lives, and country-by-country sanctions programs fall outside this post.
Onboard translators and pay them across borders in Wingspan
See how content and localization teams onboard workers, collect tax forms, and pay across borders in Wingspan.
How to Build, Manage, and Maintain Them
Build a W-9 collection and TIN matching workflow with clear owners, secure updates, mismatch resolution, and records ready for 1099 review.
Reconcile contractor payments across platforms, AP, banks, and legacy systems with source registers, recipient mapping, and a reviewable bridge.